We’ve seen buyers worry about everything inside a house, including an aging furnace, a suspicious crack in the basement wall, and roof shingles that probably should have been replaced five years earlier. Flood insurance rarely entered the conversation unless a mortgage lender brought it up.
That was how plenty of people approached the subject. If a house wasn’t sitting beside a river or along the coast, flooding seemed like somebody else’s problem.
According to the Government Accountability Office (GAO), 86% of high-risk properties have no flood insurance, while only 4% of properties nationwide carry coverage.
Standard homeowners insurance generally doesn’t cover flooding caused by rising surface water.
With millions of American properties facing flood exposure, it’s worth asking why so many homeowners are taking that risk, sometimes without even realizing it.
Millions of Homes Are at Risk, but Few Are Insured
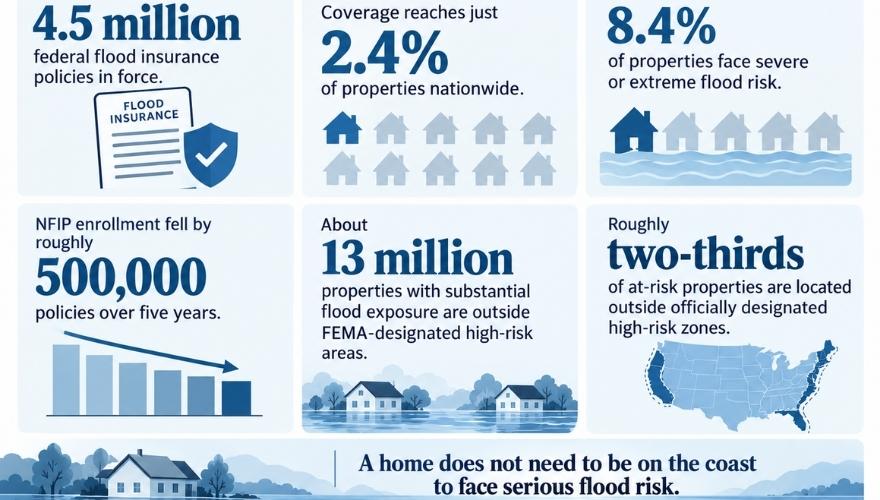
Approximately 4.5 million federal flood insurance policies are in force across the United States, covering just 2.4% of properties nationwide.
Meanwhile, an estimated 8.4% of properties face severe or extreme flood risk. Enrollment in the National Flood Insurance Program (NFIP) has also declined by roughly 500,000 policies over five years.
Fewer homeowners are carrying federal coverage at a time when flooding is becoming an increasingly serious concern in many communities. Part of the problem involves how flood risk is identified.
Federal Emergency Management Agency (FEMA) floodplain maps help determine which properties fall within designated high-risk areas. Mortgage lenders use those maps when deciding if borrowers must purchase flood insurance.
Unfortunately, a map boundary isn’t the same thing as a physical boundary for water. Approximately 13 million properties with substantial flood exposure are missing from FEMA’s designated high-risk areas.
Congressional Budget Office (CBO) research also found that roughly two-thirds of at-risk properties were located outside those officially designated zones. Geography makes another difference. Coastal homeowners are generally more accustomed to hearing about flood insurance, while people farther inland may have little reason to think about it until something goes wrong.
Federal insurance participation among at-risk properties shows just how different those attitudes and circumstances can be:
A house doesn’t need an ocean view to flood. A swollen creek, unusually heavy rainfall, or an overwhelmed drainage system can cause serious damage miles away from the coastline.
Why Homeowners Go Without Flood Insurance
Telling homeowners to purchase flood insurance sounds simple enough.
Paying for it, particularly when every other household expense seems to be increasing, is another matter.
Several factors help explain why millions of properties go uninsured.
Many Homeowners Believe They’re Already Covered
A standard homeowners insurance policy usually covers certain kinds of water damage, such as a burst pipe. Floodwater entering a house due to overflowing rivers, heavy rainfall accumulating on the ground, or storm surge is generally excluded.
A homeowner who has never read the exclusions might reasonably assume that a policy covering storms also covers flooding.
Unfortunately, insurance contracts make distinctions that weather systems don’t. Lender requirements can reinforce that misunderstanding. Flood insurance is generally mandatory for certain federally regulated or federally backed mortgages in designated high-risk flood zones.
Properties outside those areas often have no such requirement. Buyers may interpret that absence as evidence that their homes aren’t particularly vulnerable.
In reality, it may simply mean their properties fall outside the boundaries used to enforce the insurance requirement.
Insurance Has Become More Expensive
Annual premiums have become another substantial obstacle.
A typical flood insurance policy costs approximately $1,100 annually, representing an increase of roughly 90% over five years.
FEMA’s Risk Rating 2.0 pricing system was designed to align premiums more closely with individual property risks. Factors such as flood frequency, rebuilding costs, and property characteristics play a greater role in determining prices.
Although that approach aims to produce more accurate pricing, it has increased costs for many policyholders.
CBO findings indicate that approximately three-quarters of NFIP policyholders faced higher premiums.
Affordability also varies considerably across communities.
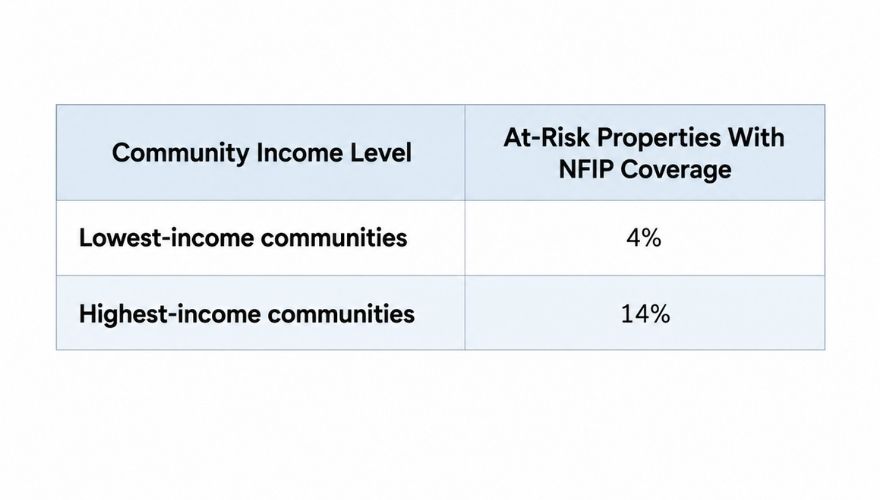
Higher-income communities had more than three times the federal insurance participation rate recorded in the lowest-income communities.
Such differences shouldn’t be surprising. A household already struggling with mortgage payments, taxes, utilities, and repairs may have difficulty finding another $1,100 each year.
We remember buyers calculating their monthly payments down to the last dollar, hoping nothing expensive would break during their first year of ownership. Flood insurance would have been a difficult addition to those budgets, particularly if nobody had identified an obvious risk.
Flood Risk Is Easy to Underestimate
Annual flood probabilities can also sound less concerning than they actually are.
Consider a property facing a 1% annual probability of experiencing a particular level of flooding. A one-in-100 chance each year sounds relatively remote.
Over a 30-year mortgage, however, that annual probability translates into approximately a 26% chance of experiencing at least one such flood, assuming the yearly probability stays constant.
That doesn’t mean every home in a designated 100-year floodplain will flood during a mortgage term. It does mean that a seemingly small annual probability becomes much more consequential when considered across decades.
Homeownership is a long commitment. Risk assessments should account for more than the next rainy season.
What Happens When an Uninsured Home Floods?
Eastern Kentucky provided a painful example in July 2022, when catastrophic flooding swept through communities, destroyed homes, and killed more than 40 people.
Many affected residents faced serious flood exposure without having insurance that could help them rebuild.
Numbers collected for the disaster reveal how poorly insurance participation matched the actual danger:
- 2.1% of properties in the affected area had flood insurance.
- 47% of properties faced severe or extreme flood risk.
- 18% of flooded buildings were located inside FEMA-designated high-risk flood zones.
That final figure is particularly troubling. Most of the buildings struck by flooding were outside the mapped zones that commonly trigger mandatory flood insurance requirements.
Residents who hadn’t been instructed to purchase coverage were not necessarily living in safe locations.
For homeowners, knowing what to do after a flood can make a big difference. Here’s a helpful guide with important insurance information to keep in mind if your home is flooded:
Two Homeowners, Very Different Financial Outcomes
Jennifer Campbell was among those whose homes suffered substantial damage. Her uninsured property sustained approximately $100,000 in losses.
Before the flooding, Campbell had the financial advantage of living without a house payment. Afterward, she had to take out a loan to recover.
Think about what that means for a household.
Years spent paying down a mortgage can provide financial security, particularly as retirement approaches.
An uninsured disaster can undo much of that progress and introduce a major debt at an age when somebody expected to have fewer monthly obligations.
What This Means for Homebuyers and Homeowners
Flood exposure deserves consideration alongside property taxes, insurance premiums, structural condition, and other routine housing expenses.
Buyers already have plenty to investigate before closing. Still, discovering a property’s flood risk after taking ownership is considerably less useful than learning about it beforehand.
Check Flood Risk Before Buying
A property’s location outside FEMA’s designated high-risk zones shouldn’t end the investigation.
Buyers should review available flood-risk information, ask about previous water damage, and consider local drainage conditions.
Several practical questions deserve attention:
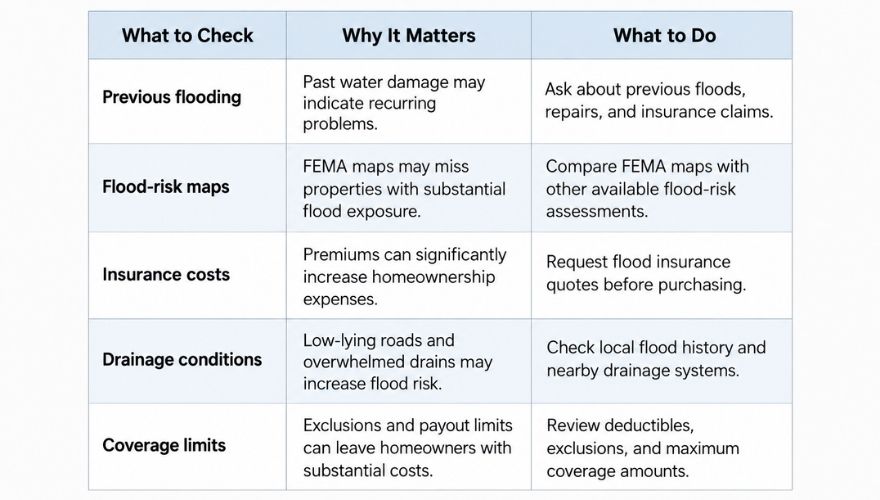
No single answer guarantees that a home is safe. Together, however, these questions can help buyers make a more informed decision.
Flood Insurance Can Change the Cost of Ownership
Insurance premiums deserve particular attention because they can substantially alter a household budget.
Consider a Louisiana homeowner who reported dropping flood coverage after his annual premium increased from $900 to $4,000.
That represents an additional $3,100 each year, or about $258 per month. For some households, an increase of that size could consume the money previously allocated for repairs, savings, or other necessities.
Dropping coverage eliminates the premium but leaves the owner responsible for qualifying flood losses that insurance otherwise might have covered.
In an area with significant flood exposure, homeowners are effectively deciding how much financial risk they can afford to carry themselves.
Coverage Limits Matter, Too
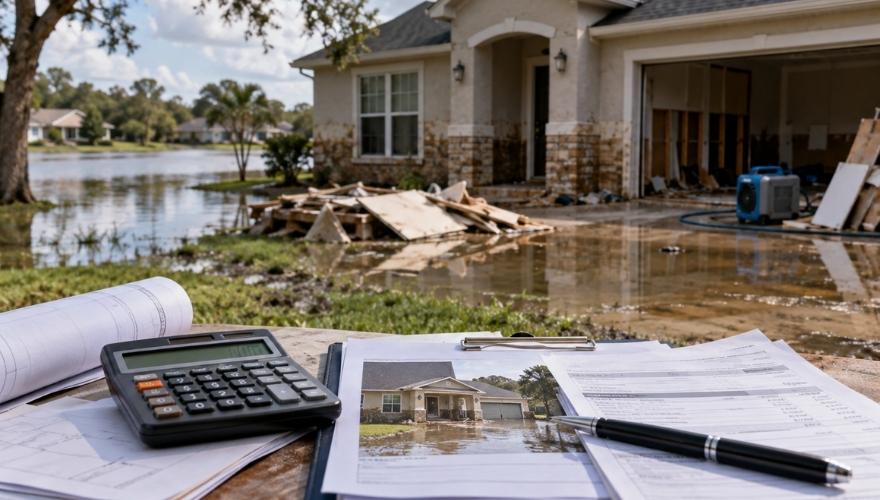
Purchasing flood insurance doesn’t automatically mean every dollar of damage will be covered.
Depending on the home’s rebuilding costs and the value of its contents, those limits may be insufficient.
Private flood insurance may offer different limits and terms, making comparisons worthwhile. Buyers should also consider how flood exposure could influence a property’s future desirability and resale value.
Expensive coverage, documented flood damage, and recurring water problems may make a house more difficult to sell, although effects vary considerably by market and property.
A low purchase price isn’t necessarily a bargain if ownership brings unusually high insurance costs and recurring damage risks.
The Cost of Being Unprepared
Millions of American homeowners face flood risks without the insurance needed to protect them against potentially serious financial losses.
It would be convenient to blame the situation entirely on homeowners neglecting to purchase coverage. Available evidence suggests a more complicated problem.
Incomplete flood maps, rising premiums, limited awareness, and insurance requirements that don’t cover every vulnerable property all contribute to the gap.
Federal policymakers also face a difficult financial question. NFIP carries more than $20 billion in debt while attempting to provide coverage at prices homeowners can afford.
Home Stats Report
Home Stats Report takes a practical, numbers-first look at the American housing market, drawing on decades of real estate experience, historical trends, and the everyday realities of buying and selling homes. Housing has never been as simple as a headline suggests. Home prices rise, mortgage rates change, inventory tightens, and buyers adjust their expectations. Home Stats Report provides market commentary, analysis, and general information for educational purposes only. We do not offer financial, investment, mortgage, or real estate advice.
All reports by Home Stats Report